
What Is Dollar-Cost Averaging in Crypto?
Dollar-cost averaging means buying a fixed amount at regular intervals. How DCA works in crypto, a worked example, how it compares with lump sums, its limits.
Dollar-cost averaging (DCA) means buying a fixed dollar amount of a crypto asset at regular intervals, such as $100 a month, whatever the price. You buy more units when prices are low and fewer when high, smoothing your average cost without timing the market. It does not guarantee profit or protect against long declines.
How it works
You pick an amount, an asset and a schedule, then buy on that schedule. Many exchanges offer recurring buys that do this automatically. Because the dollar amount is fixed, the number of coins you get each time changes with the price.
Worked example
You invest $100 a month for four months in bitcoin, at prices of $50,000, $40,000, $25,000 and $50,000 (illustrative).
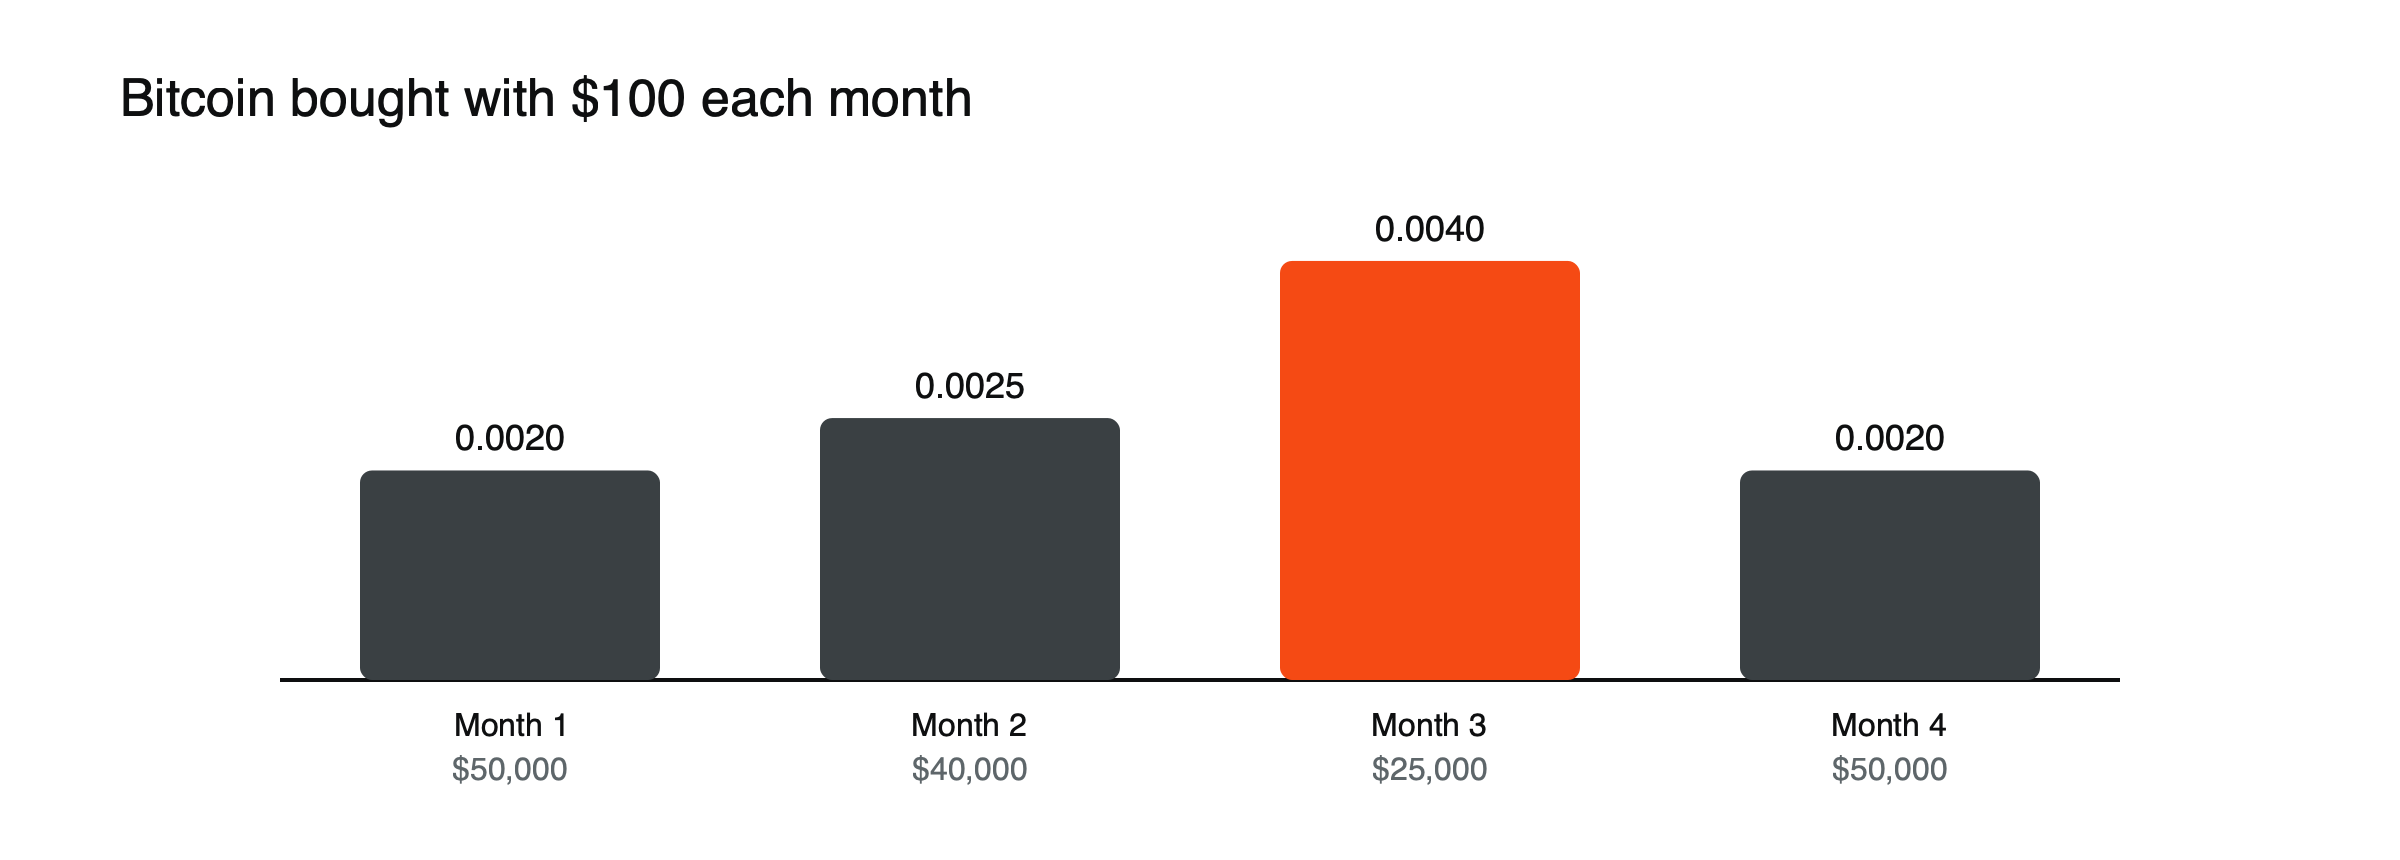
Figure: The same $100 buys more bitcoin when the price is lower (illustrative prices).
| Month | Price | Bitcoin bought |
|---|---|---|
| 1 | $50,000 | 0.0020 |
| 2 | $40,000 | 0.0025 |
| 3 | $25,000 | 0.0040 |
| 4 | $50,000 | 0.0020 |
| Total | 0.0105 for $400 |
Your average cost is $400 ÷ 0.0105 ≈ $38,095, below the starting price. At $50,000, your holding is worth $525. Investing $400 at once in month 1 would have bought 0.008 BTC, worth $400 at the same end price.
When DCA does not help
If prices keep falling, DCA still loses money. Buying $100 a month at $50,000, $40,000, $30,000 and $20,000 gives about 0.0128 BTC, worth about $257 at $20,000, a loss of about 36% on $400. DCA lowers the average cost; it does not change the direction of the market.
DCA through a full crypto cycle
DCA’s character shows most clearly across a whole market cycle. Someone who started buying near a peak would have seen their early purchases fall sharply in value, while later purchases, made during the bear market, bought far more coins for the same money. Their average cost would have fallen steadily below the early purchase prices, so a partial recovery could bring the whole position back into profit before the price returned to its starting level. (Illustrative pattern.) The approach needs patience and money to keep investing through long declines, and it does not guarantee a recovery.
DCA vs lump sum
A 2012 Vanguard study of stock and bond portfolios in the US, UK and Australia found that investing a lump sum at once beat spreading it out about two-thirds of the time, because markets rose more often than they fell. DCA’s advantage is lower regret and less risk of investing everything just before a fall. These findings come from traditional markets, not crypto, which is far more volatile.
Who DCA suits
- People investing from regular income rather than a one-off sum.
- Anyone who wants to avoid trying to time the market.
- Long-term holders of assets they understand.
Weekly, monthly or daily?
The frequency matters less than sticking to the plan. More frequent purchases smooth the average price slightly more, but each small purchase may carry a minimum fee that takes a larger share of a small amount. For most people, weekly or monthly buys tied to their pay schedule balance smoothing with costs.
Variations on DCA
Some investors adjust the basic method. Value averaging aims for the holding to grow by a set amount each period, buying more after falls and less, or even selling, after rises. Others keep a fixed schedule but add an extra purchase after large drops. These variations can improve results in some markets but add decisions and complexity, which works against DCA’s main advantage: removing the need to judge the market.
DCA when selling
The same idea works in reverse. Someone planning to reduce a large crypto holding can sell a fixed amount on a schedule rather than all at once, avoiding the risk of selling everything at a bad moment. It also spreads any taxable gains across a longer period, which can matter in some tax systems.
What DCA cannot do
DCA is a way of entering a position, not a way of choosing one. It does not protect against an asset that never recovers, does not remove volatility from the holding once bought and does not tell you when to sell. It also tends to underperform a lump sum when prices rise steadily, because money waiting to be invested misses part of the rise. Its main value is behavioral: it replaces the hard decision of when to buy with a routine that is easy to follow.
Automating it safely
Most exchanges let you set recurring purchases from a bank account or card. A few habits keep that routine safe: check the fee on each recurring buy, since card purchases can cost far more than bank transfers; review the schedule periodically rather than letting it run unnoticed for years; and withdraw accumulated coins to a wallet you control from time to time, rather than leaving a growing balance on the exchange. See custodial vs non-custodial wallets.
Measuring how DCA is doing
Judging a DCA plan by today’s price alone can be misleading. A more useful measure compares the current value of your holding with the total amount you have put in, alongside your average cost per coin. If the asset trades above your average cost, the plan is in profit even if the latest purchases are below water. Tracking just these two numbers every few months or so, rather than checking the price daily, matches the long horizon the method is built for. It also helps to note what share of your total savings the plan now represents, since a steady schedule in a rising market can quietly grow a holding beyond the size you originally intended for it. Rebalancing back to your target share, or pausing contributions for a little while, keeps the plan aligned with the risk you chose at the start.
Costs and practical points
Frequent small purchases can mean higher fees as a share of each buy. Compare recurring-buy fees with regular trading fees, and keep records of every purchase for tax purposes. See how to compare crypto exchange fees and how to keep crypto transaction records. For the basics of buying, read what a cryptocurrency exchange is.
This article is educational content and does not constitute financial, investment, legal or tax advice. Digital assets are volatile and you may lose the amount you invest.
Frequently asked questions
Does DCA work for altcoins?
The method works the same way, but it cannot make a failing asset succeed. DCA into a token that keeps falling or stops trading simply buys more of a losing asset. It suits assets you expect to hold for many years.
Should I stop DCA in a bear market?
That depends on your plan and finances, not on the market alone. Bear markets are when DCA buys the most coins per dollar, but only money you will not need for years should be invested that way.