
What Are Inverse ETFs?
Inverse ETFs aim for the opposite of an index's daily return. Because they reset daily, longer-term results can drift far from the inverse. How they work.
Inverse ETFs aim to deliver the opposite of an index’s return over a single day, using futures or swaps: if the index falls 1% today, a −1x inverse ETF aims to rise about 1%. Because they reset daily, returns over weeks or months can differ sharply from the index’s inverse. They are built for short-term use.
How they work
The fund uses derivatives to take a short position equal to its assets, then rebalances daily so the next day starts at the target exposure.
Why longer-term results drift
Example: an index goes from 100 to 110 (+10%), then back to 100 (−9.09%). It ends flat. A −1x inverse ETF falls 10% to 90, then rises 9.09% to about 98.2, a loss of about 1.8% even though the index ended where it started. (Example values.)
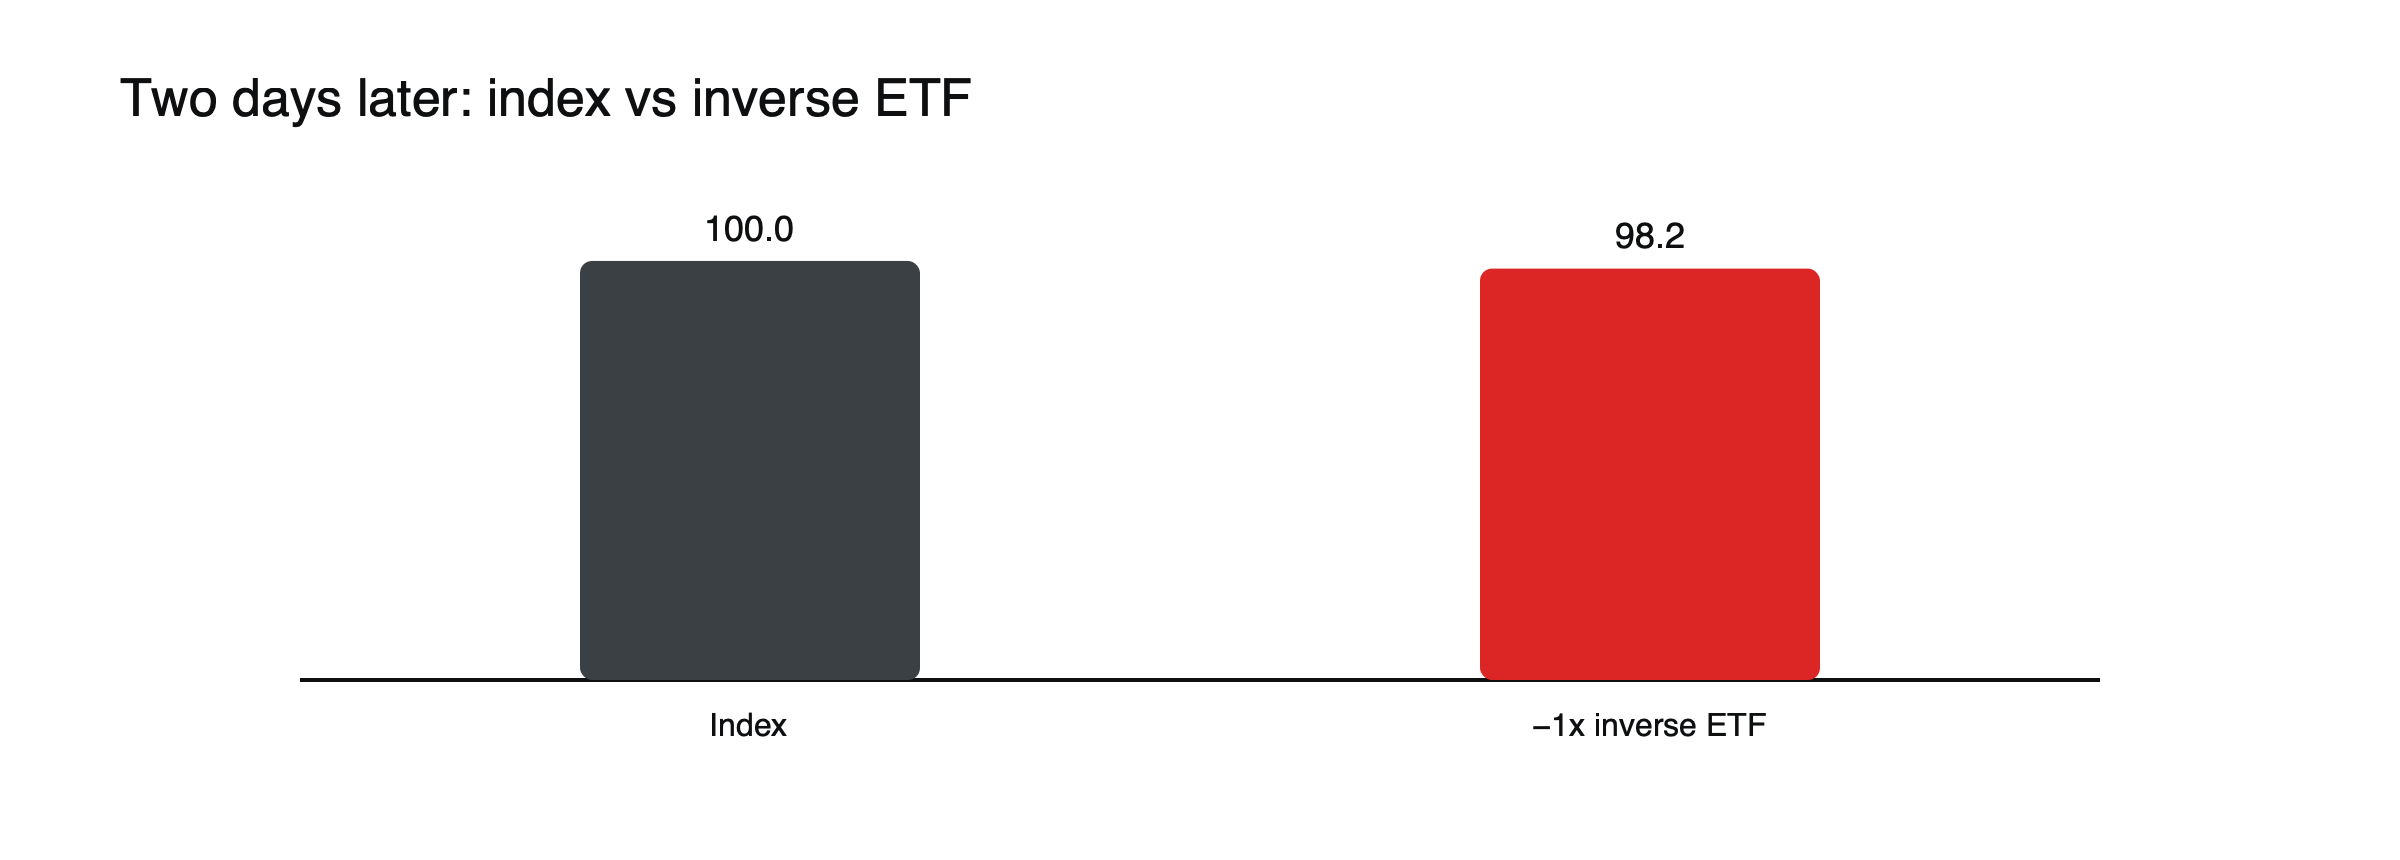
Figure: Daily reset drift (example values).
This effect grows with volatility and with leverage. See how volatility decay erodes leveraged ETF returns.
Ten choppy days, illustrated
Suppose an index alternates between rising 3% and falling 3% for ten trading days. It ends about 0.45% lower. A −1x inverse ETF, which might be expected to gain about 0.45%, actually ends about 0.45% lower too, and a −2x inverse ETF ends about 1.8% lower. (Example values, before fees.) In a sideways, volatile market, both the index and its inverse can lose money at the same time.
A steady decline, illustrated
Now suppose the index falls 1% every day for ten days, a total decline of about 9.6%. A −1x inverse ETF rises about 1% a day, compounding to a gain of about 10.5%, slightly more than the index’s fall. In steady trends, daily resetting can work in the holder’s favor; the problem is that trends rarely move in straight lines. (Example values.)
Who uses them
Traders seeking short-term downside exposure or hedges without a margin account.
Risks
- Compounding drift over periods longer than a day.
- Higher fees than plain index ETFs.
- Leveraged inverse versions (−2x, −3x) magnify everything.
Holding periods
Inverse ETFs are designed to deliver their target over one day. Fund documents usually warn that returns over longer periods can differ significantly from the inverse of the index. Many professional users hold them for hours or days, checking positions daily, rather than treating them as long-term hedges.
Inverse ETFs vs shorting with CFDs
A short CFD tracks the index’s inverse continuously rather than resetting daily, but carries financing and margin requirements. See how short selling works with CFDs and what an ETF is.
How inverse ETFs are built
The fund typically holds cash and short-term government securities and enters into swaps or sells futures equal to its assets. At the end of each day, it adjusts those positions so that its exposure is again equal to −1 times, or −2 or −3 times, its assets. After a day when the index falls, the fund’s assets have grown and it must increase its short exposure; after a rise, it must reduce it. That daily rebalancing is the source of both the compounding effects and, in large funds, trading at the close.
Inverse ETFs as hedges
An investor holding shares can buy an inverse ETF to offset part of a market decline without selling, and without a margin account. Over a few days, the hedge can work well. Over months, especially in volatile markets, the hedge’s value can drift away from the intended offset, and the investor may find it has lost money even if the market has fallen modestly overall. Reviewing and resetting the hedge regularly reduces that drift.
Fees and costs
Inverse ETFs usually charge much higher fees than plain index ETFs, often around 1% a year, and bear the costs of their derivatives. Those costs add to the drag from daily resetting over long holding periods.
Comparing with a short CFD
| Inverse ETF | Short CFD | |
|---|---|---|
| Exposure | Resets daily | Fixed size until changed |
| Account needed | Ordinary brokerage account | CFD account with margin |
| Maximum loss | Amount invested | Can exceed margin, limited by negative balance protection for EU retail |
| Holding cost | Fund fee and derivative costs | Daily financing |
| Long-term tracking | Drifts in volatile markets | Follows the price directly |
Inverse ETFs in a sharp fall, illustrated
Suppose an index falls about 12% in a single day, as the S&P 500 did on March 16, 2020. A −1x inverse ETF would rise about 12% that day, before fees, and a −2x version about 24%. (Example values.) On days like these, inverse ETFs work as intended. The difficulty lies in the days that follow, when markets swing sharply in both directions and daily resetting starts to erode results.
Leveraged inverse funds
Funds aiming for −2x or −3x the daily return magnify both the gains on falling days and the losses on rising days, and their drift over time is larger. In volatile, sideways markets, they can lose a large share of their value even if the index ends lower. They are among the riskiest ETFs available to individual investors.
Inverse bond and commodity funds
Inverse funds exist for bonds, currencies and commodities as well as shares, offering ways to profit from rising interest rates or falling commodity prices. The same daily-reset mechanics apply, and futures-based funds also face rolling costs.
Monitoring
Holders of inverse ETFs should compare the fund’s performance with the index each day and decide whether to keep, adjust or close the position. Setting a maximum holding period in advance helps avoid drifting into a long-term position by accident.
Common misreadings
- Expecting the exact inverse of the index over weeks or months.
- Using leveraged inverse funds as long-term hedges.
Inverse ETFs and put options
Put options on an index or ETF also gain when markets fall, but their maximum loss is the premium paid, and they do not suffer from daily resetting. They do lose value as time passes if the market does not fall. For hedging a specific period, options can be more predictable than inverse ETFs, though more complex to use.
Taxes and reporting
Inverse and leveraged ETFs can distribute capital gains generated by their derivatives, and their tax treatment varies by country and product structure. Checking how such funds are taxed locally avoids surprises at year end.
Choosing a product
Compare the index tracked, the leverage, fees, fund size, daily trading volume and how closely the fund has met its daily target in the past. Larger, more liquid funds usually track their daily objective more reliably.
Inverse funds on volatile markets
Inverse funds tracking volatile indices, such as technology-heavy or small-company indices, suffer more drift than those on calmer markets, because daily swings are larger. Over a choppy month, a −2x fund on a volatile index can lose money even if the index falls. Choosing the least volatile index that matches the hedge needed reduces this effect.
A checklist before buying
- What exactly are you hedging or betting against?
- For how many days will you hold?
- Is the fund leveraged, and how volatile is its index?
- What does it cost per year?
- How will you check whether it is still doing its job?
After the hedge
Once the reason for an inverse position has passed, closing it promptly avoids the slow erosion that daily resetting causes in choppy markets. Reviewing the result against the original aim, and against what a short CFD or options hedge would have cost, shows which tool suits future hedges best. Keeping a record of each hedge, its cost and its outcome makes the next decision faster and better informed.
Frequently asked questions
Can an inverse ETF fall to zero?
Leveraged inverse funds can lose almost all their value in a very sharp rally. Unleveraged ones can lose heavily in strong rallies, though a complete loss would require the index to double in a day.
Are inverse ETFs suitable for long-term holding?
They are generally designed for short-term use; their documents usually say so explicitly.
Leverage, margin and cost figures in this article are example values for illustration. Actual terms depend on the provider, the instrument and the rules in your country.
This article is educational content and does not constitute financial, investment, legal or tax advice. Digital assets are volatile and you may lose the amount you invest.
Sources
- The day the VIX doubled (inverse and leveraged daily-reset products can collapse in a single move, as XIV did in 2018) — Bloomberg
- Volatility gauge tops 50 (feedback loops in inverse volatility products) — Bloomberg via BNN
- What investors need to know about volatility and the VIX (S&P 500 −11.98% on March 16, 2020) — John Hancock Investment Management