
Tokenized Deposits vs Stablecoins
Tokenized deposits are bank deposits on a blockchain; stablecoins are claims on an issuer's reserves. Compare who issues them, insurance, interest and access.
The key difference in tokenized deposits vs stablecoins is the legal claim. A tokenized deposit is a bank deposit recorded on a blockchain, so the holder is the bank’s depositor. A stablecoin is a claim on a separate issuer’s reserves. Deposit tokens can pay interest and may carry deposit insurance; payment stablecoins generally cannot.
How tokenized deposits work
A bank creates a token that represents dollars on deposit with it, one for one, and keeps its ledger and the blockchain in step. JPMorgan’s JPMD, also called JPM Coin, is the best-known example: it moved into institutional use on Coinbase’s Base network on November 12, 2025.
How stablecoins work
An issuer such as Circle or Tether takes dollars, holds reserves and issues tokens anyone can hold and transfer. See what a stablecoin is and centralized vs decentralized stablecoins.
Side by side
| Tokenized deposit | Stablecoin | |
|---|---|---|
| Issuer | A regulated bank | A stablecoin company |
| Holder’s claim | A bank deposit | A claim on the issuer’s reserves |
| Interest | Can pay interest | US and EU payment stablecoins may not |
| Deposit insurance | May apply, within limits | Does not apply |
| Who can hold it | Usually the bank’s clients, often institutions | Anyone with a compatible wallet |
| Price at par | Settles at face value between accounts | Can trade slightly above or below $1 |
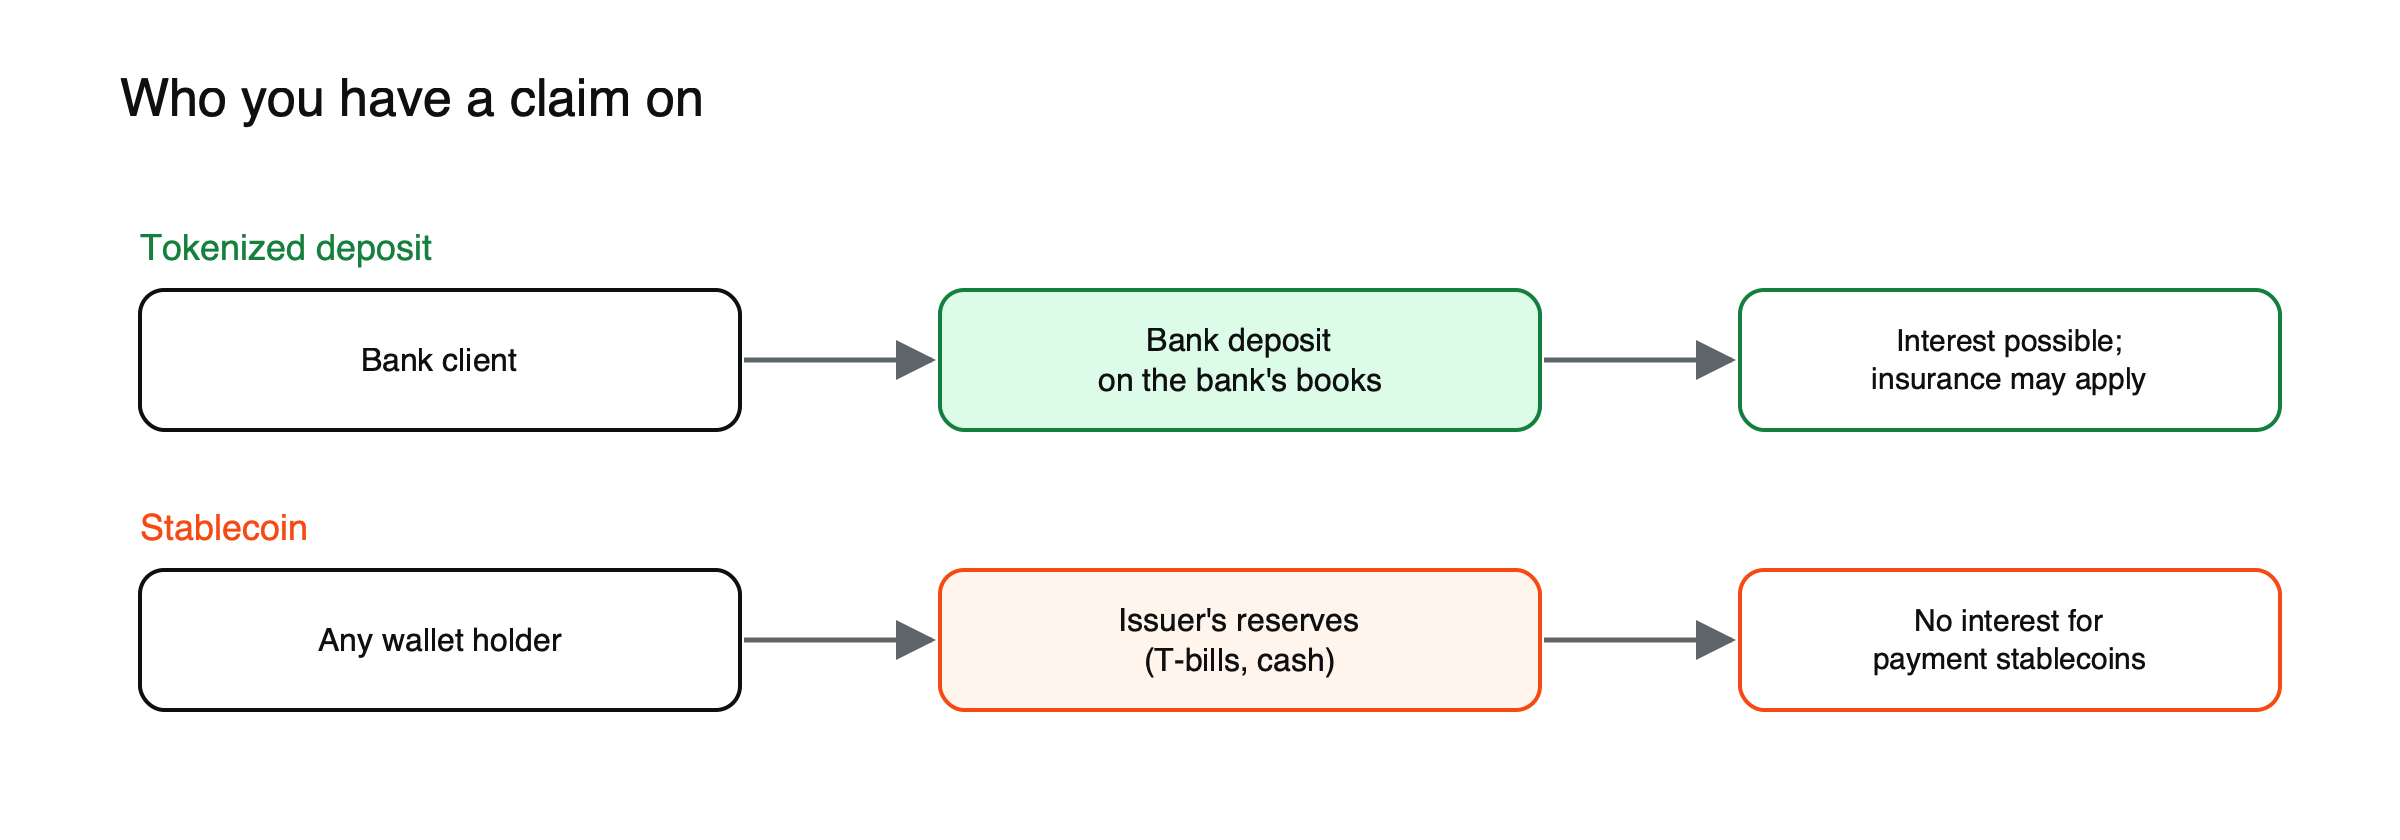
Figure: Who you have a claim on in each model.
When the safer-sounding option is the wrong fit
Deposit tokens sound safer, and for a bank’s institutional clients they often are. But they are usually limited to that bank’s customers and permissioned uses. For people without good banking access, or who need to move money across platforms and borders, an openly transferable stablecoin is more useful. Supervisors are also still working out how insurance applies when deposit tokens move on public networks.
A payment between two companies
Suppose two companies need to settle a $5 million invoice on a Saturday. (Illustrative scenario.) If both bank with the same institution and it offers deposit tokens, the payment can move between their accounts on the bank’s network within minutes, staying a bank deposit throughout. If they bank with different institutions, both banks must support a shared network, or the payment waits for traditional rails. A stablecoin can move between any two compatible wallets at any hour, but the receiving company then holds a claim on the stablecoin issuer until it redeems or converts the tokens. Which option works best depends less on technology than on who the two parties bank with.
Banks also bring familiar obligations along with them. A deposit token is subject to the same identity checks, sanctions screening and reporting as any other bank account, which suits corporate treasurers but makes it a poor fit for anyone who wants to transact without opening an account with that particular bank first.
Interest and insurance in detail
Because a tokenized deposit is a deposit, a bank can pay interest on it, and deposit insurance may apply up to the usual limits, such as $250,000 per depositor per bank in the United States. Large corporate balances usually exceed those limits, so for big holders the practical protection is the bank’s own strength and regulation. How insurance applies to deposit tokens moving on public blockchains is still being worked out. Payment stablecoins under US and EU rules may not pay interest, and holders rely on reserves and regulation rather than insurance.
Public chains and permissioned access
Some deposit tokens now run on public blockchains: JPMorgan’s JPMD moved onto Base, an Ethereum layer 2 network, in November 2025. Running on a public chain does not make the token open to everyone. Access is still limited to the bank’s verified clients, and transfers outside that group are blocked. The public chain mainly provides shared infrastructure and the ability to interact with other on-chain systems.
The interoperability problem
A deposit token from one bank is not the same as a deposit token from another, any more than a balance at one bank is a balance at another. Without a shared network, each bank’s token works mainly among its own clients. That is why large US banks have been building a common tokenized deposit network through The Clearing House, targeting the first half of 2027, and why stablecoins, which work across platforms by design, still dominate open crypto markets.
How regulators are leaning
Several central bankers and regulators outside the United States have signaled a preference for tokenized deposits over privately issued stablecoins, including the Governor of the Bank of England, partly because deposits sit inside the existing banking system with its capital rules and supervision. In the United States, new legislation created a path for regulated payment stablecoins while banks develop deposit tokens in parallel. The direction of policy may shape which form grows faster in each region.
What it means for crypto users
For most people active in crypto today, stablecoins remain the practical option: they are accepted across exchanges, wallets and applications, and anyone can hold them. Tokenized deposits matter mainly behind the scenes, in how banks, payment firms and large companies settle with each other. Over time, deposit tokens could make it easier for businesses to move between bank money and on-chain activity, but the choice for an individual user is still mostly between different stablecoins.
What comes next
JPMorgan, Citi, Bank of America and Wells Fargo have been building a shared tokenized deposit network through The Clearing House, targeting the first half of 2027. Some regulators outside the US, including the Bank of England’s governor, have said they prefer tokenized deposits to bank-issued stablecoins.
For the wider category, read what RWA tokenization is and stablecoin regulation in the EU vs US.
This article is educational content and does not constitute financial, investment, legal or tax advice. Digital assets are volatile and you may lose the amount you invest.
Frequently asked questions
Can individuals use tokenized deposits?
Mostly not yet. Current products focus on institutional clients and business payments. Retail access depends on banks offering deposit tokens to everyday customers, which few have done.
Will tokenized deposits replace stablecoins?
Unlikely in open crypto markets, where stablecoins are already embedded and can be held by anyone. More likely, both will coexist: deposit tokens for bank clients and regulated settlement, stablecoins for open networks and global users.
Sources
- What Is a Tokenized Deposit? (JPMD on Base from November 12, 2025; deposit insurance and interest; BIS framing; payment stablecoins cannot pay yield) — Eco
- JPMorgan says regulators outside US appear to prefer tokenized bank deposits (Bank of England governor; settle at face value) — The Block, July 2025
- Stablecoins vs Tokenised Deposits (Tokenized Deposit Network via The Clearing House targeting H1 2027; insurance questions on public chains) — Banxa
- Deposit insurance FAQs (standard coverage of $250,000 per depositor, per insured bank, per ownership category) — FDIC