
What Caused the 1997 Asian Financial Crisis?
On July 2, 1997, Thailand stopped defending the baht's peg. The crisis spread to Indonesia and South Korea, needing record IMF packages. Causes and lessons.
The Asian financial crisis began on July 2, 1997, when Thailand, after spending billions in reserves, stopped defending the baht’s dollar peg. The baht lost about half its value and the crisis spread to Indonesia and South Korea. IMF packages reached about $17 billion for Thailand, $40 billion for Indonesia and $57 billion for Korea.
The boom before the bust
Through the early 1990s, capital poured into fast-growing economies such as Thailand, Indonesia, Malaysia, the Philippines and South Korea. Growth was strong, and pegs or tightly managed exchange rates against the dollar made it look safe for local banks and companies to borrow cheaply in dollars and lend or invest in local currency. Thailand’s baht had been held at around 25 to the dollar for about a decade. Much of the borrowing was short-term, and a large share went into property and stock markets, which rose rapidly. When US interest rates rose and the dollar strengthened in the mid-1990s, currencies pegged to it became less competitive, export growth slowed and the cracks began to show.
Causes
- Pegged currencies that encouraged borrowing in dollars.
- Heavy short-term foreign debt, mostly owed by private companies and banks.
- Weak financial supervision and property bubbles.
- Sudden capital flight once confidence cracked.
Why pegs and dollar debt are a dangerous mix
Suppose a Thai property developer borrowed $10 million when the baht was pegged at about 25 to the dollar, receiving roughly 250 million baht to spend on local projects. (Illustrative example.) Its income from rents and sales was in baht. When the baht fell to about 50 to the dollar, the same $10 million debt was worth about 500 million baht, double what the company had borrowed, while its property was falling in value. Thousands of companies and banks were in similar positions, so the currency’s fall turned into a wave of defaults. Those defaults weakened banks, which made foreign lenders even keener to pull money out, which pushed the currency down further. A peg encourages exactly the borrowing that makes its eventual break most damaging, because it hides the currency risk until it arrives all at once. Companies that had hedged their dollar debt, or borrowed in their own currency, came through the crisis in far better financial shape.
Timeline
- May 1997: speculative attacks on the baht.
- July 2, 1997: Thailand floats the baht after using about $33 billion in reserves defending it.
- July 11: the Philippine peso is devalued; Indonesia widens the rupiah’s trading band.
- August 1997: Thailand agrees an IMF-led package of about $17 billion; Indonesia lets the rupiah float, and it falls 30% in two months.
- October–November: Indonesia’s package grows to about $40 billion; South Korea requests IMF help.
- December 3: South Korea and the IMF agree a $57 billion package.
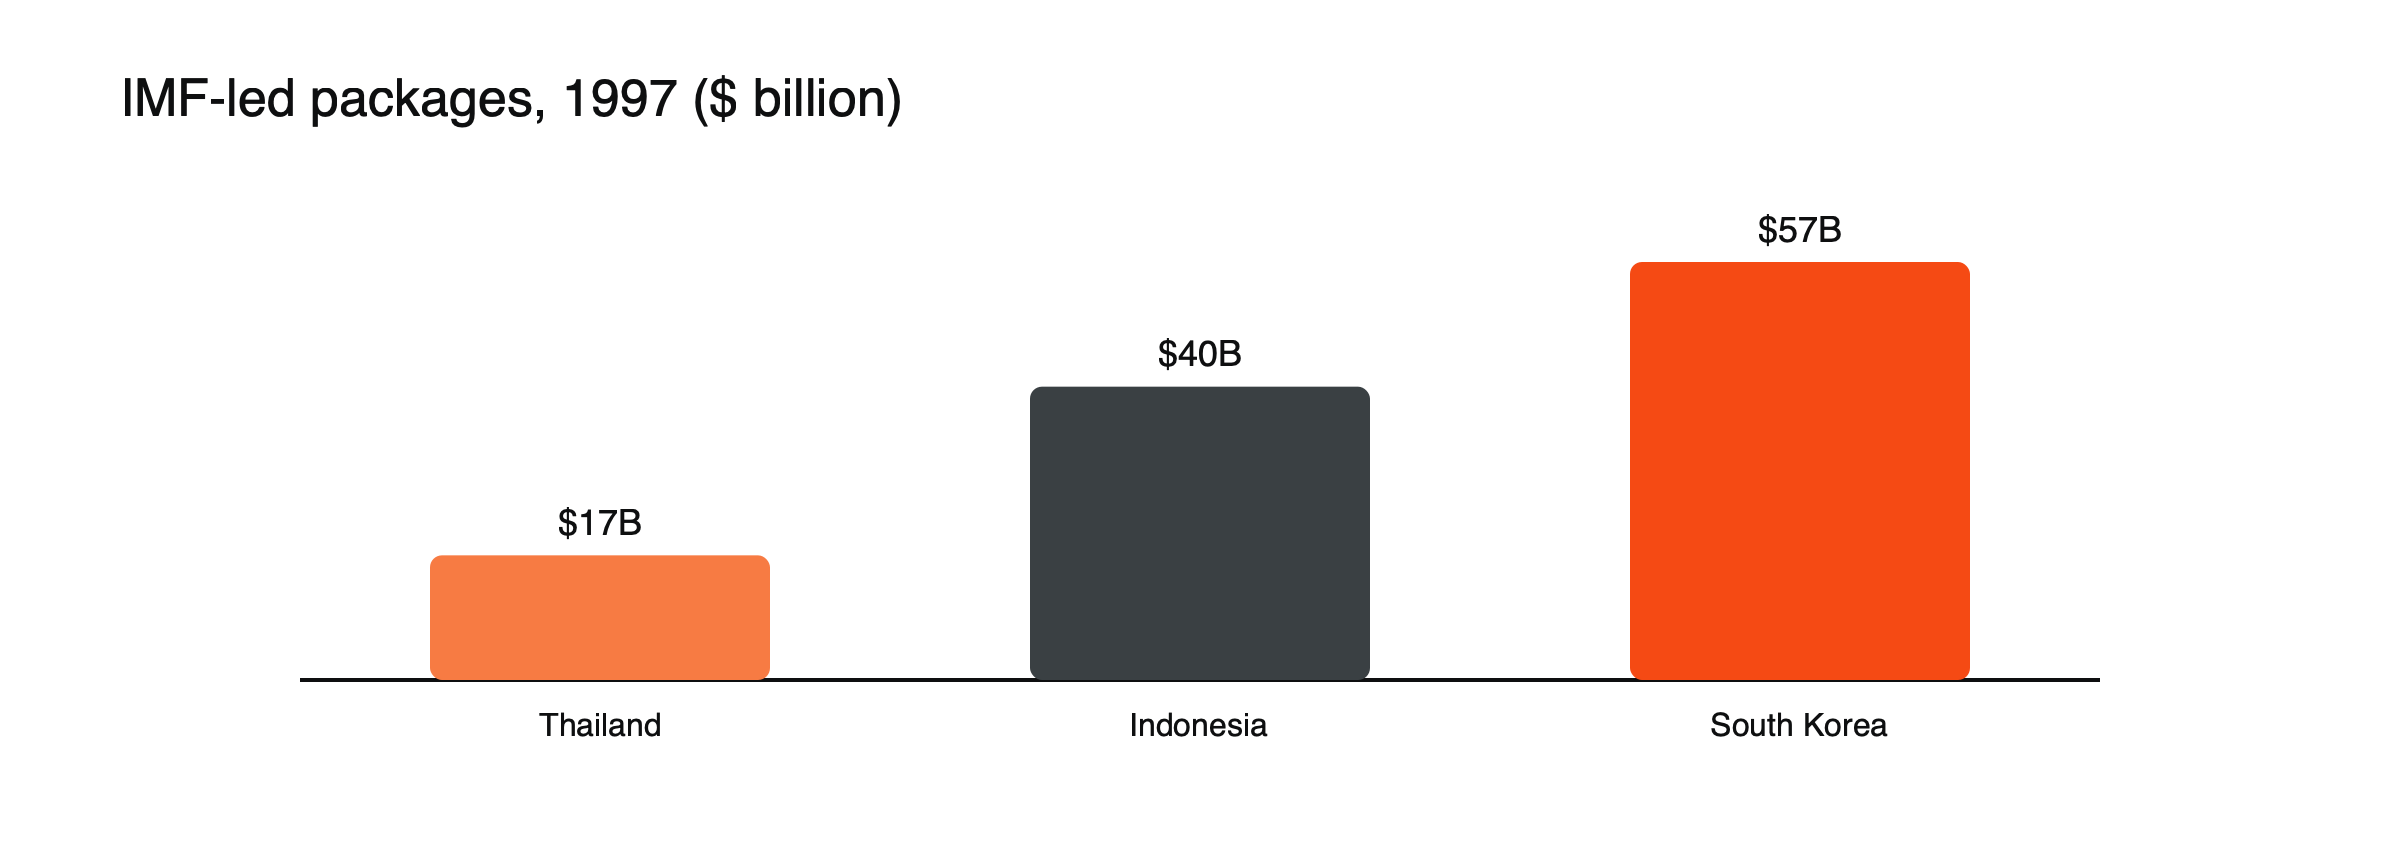
Figure: IMF-led packages in 1997. Sources: CRS; Advisor Perspectives.
How far the currencies fell
| Currency | Before the crisis, per dollar | At or near its low | Approximate loss by January 1998 |
|---|---|---|---|
| Thai baht | About 25 | About 53 in January 1998 | 56% |
| Indonesian rupiah | About 2,400 | Close to 15,000 by June 1998 | 81% |
| Malaysian ringgit | About 2.50 | As weak as 4.88 | 46% |
| Philippine peso | — | — | 41% |
| South Korean won | About 900 | Close to 1,700 | Fell 55% to its December low |
(Figures rounded from contemporary reports.) Moves of this size would wipe out most leveraged positions many times over, and they happened in currencies that had barely moved for years.
Contagion
The speed with which the crisis spread surprised policymakers. Malaysia abandoned its peg on July 14, 1997, and Indonesia floated the rupiah on August 14. Investors who had treated Southeast Asia as a single opportunity now treated it as a single risk, selling currencies, shares and bonds across the region regardless of each country’s situation. South Korea, a much larger and more industrial economy, was hit by the end of the year as foreign banks refused to roll over short-term loans; Seoul stopped defending the won in November, and it fell below 1,000 to the dollar. Hong Kong kept its currency peg, but at the cost of high interest rates and a sharp fall in asset prices.
Effects
Currencies and stock markets across the region plunged, several economies contracted, and the crisis contributed to Russia’s 1998 default and market turmoil elsewhere.
Indonesia: from currency crisis to political crisis
Indonesia suffered the worst currency collapse. Doubts about its banks, its policies and the health of President Suharto drove the rupiah through successive thresholds, and early in 1998 a budget seen as reneging on IMF commitments sent it falling sharply in two days. Soaring prices for imported goods led to widespread rioting, and Suharto, in power since the 1960s, resigned on May 21, 1998.
Malaysia’s different path
Malaysia rejected an IMF program. On September 1, 1998, it imposed sweeping capital controls, and the next day fixed the ringgit at 3.80 to the dollar, about 10% stronger than where it had been trading just before. The measures were widely criticized at the time, and the economy shrank by about 6.7% in 1998, but the controls did stabilize interest rates and the currency, and the restrictions were gradually relaxed. Economists still debate whether Malaysia’s route was better or worse than the IMF approach used elsewhere.
The IMF’s role and the debate it started
The IMF packages came with conditions: higher interest rates to support currencies, budget tightening and the closure or restructuring of weak banks. Critics argued that these measures deepened the recessions; defenders said they were needed to restore confidence. The debate changed how the IMF and governments approached later crises, and it pushed many Asian countries to build very large foreign exchange reserves so they would never need such help again.
Lessons
Fixed exchange rates combined with large foreign-currency debt are fragile; reserves can run out quickly; contagion spreads through investors who treat a region as one. See fixed vs floating exchange rates, how emerging market currencies behave when risk appetite falls and how the forex market works.
What it means for traders today
The Asian crisis is a reminder that low volatility in a pegged or managed currency can hide large risks, and that the move, when it comes, can be many times larger than anything seen before. For traders in emerging market currencies today, it shows why spreads widen, liquidity disappears and correlations across a region jump during stress. Watching reserves, short-term foreign debt and current account balances helps judge which currencies are most exposed when global risk appetite falls. See what a safe-haven currency is and Black Wednesday.
Frequently asked questions
Why did the crisis start in Thailand?
Thailand combined a long-standing dollar peg, heavy short-term foreign borrowing, a property bubble and weakening exports. Once speculators doubted the peg and reserves ran low, it gave way first.
Could it happen again?
The same combination of pegs, large foreign-currency debt and thin reserves can still cause crises, but many Asian economies now hold far larger reserves and use more flexible exchange rates than in 1997.
This article is educational content and does not constitute financial, investment, legal or tax advice. Digital assets are volatile and you may lose the amount you invest.
Sources
- The Asian economic crisis and the IMF (July 2, 1997; baht lost half its value; rupiah −30% in two months; Indonesia $40 billion) — Advisor Perspectives
- The 1997–98 Asian financial crisis (Thailand used $33 billion before floating; $17.2 billion package; Korea $57 billion on December 3) — Congressional Research Service, 1998
- Timeline of the panic (Philippine peso devalued July 11; largest IMF package) — PBS Frontline
- Southeast Asian Affairs 1998 (debts mainly private; causes debated) — Cambridge Core
- 1997 Asia financial crisis (baht −56%, peso −41%, ringgit −46%, rupiah −81% by January 1998; Malaysia floated July 14, Indonesia August 14; won −55% to its December low) — Goldman Sachs history
- Is a currency crisis looming? (baht 26 to 53; won 900 to almost 1,700; rupiah 2,400 to almost 15,000; ringgit 2.50 to 4.88; peg at RM3.80) — The Star, June 2026
- The evolution of the crisis (baht around 25 for a decade; won below 1,000 in November 1997; Suharto resigned May 21, 1998) — Asiaweek via CNN
- Did the Malaysian capital controls work? (ringgit fixed at RM3.80, a 10% appreciation) — NBER Working Paper 8142
- IMF concludes Article IV consultation with Malaysia (real GDP −6.7% in 1998; capital controls and peg from September 1998) — IMF, 1999